

On Friday, Dated Brent was assessed at $116.58 a barrel, which was $9.39 lower than the previous session, when it was assessed at $125.97.
The habitual market commentators, with their perpetual bearish oil bias, jumped at the opportunity to suggest that it was a repeat of what happened in April, with physical scarcity disappearing.
I would highly recommend you take with a grain of salt anything that comes from an economist or any pundit who doesn’t actually have to be right about investment decisions and can just comment on markets and the economy at will.
Because on the very same day, the December Brent contract settled at $109.86, which was $3.94 higher than the previous day, when it closed at $105.92.
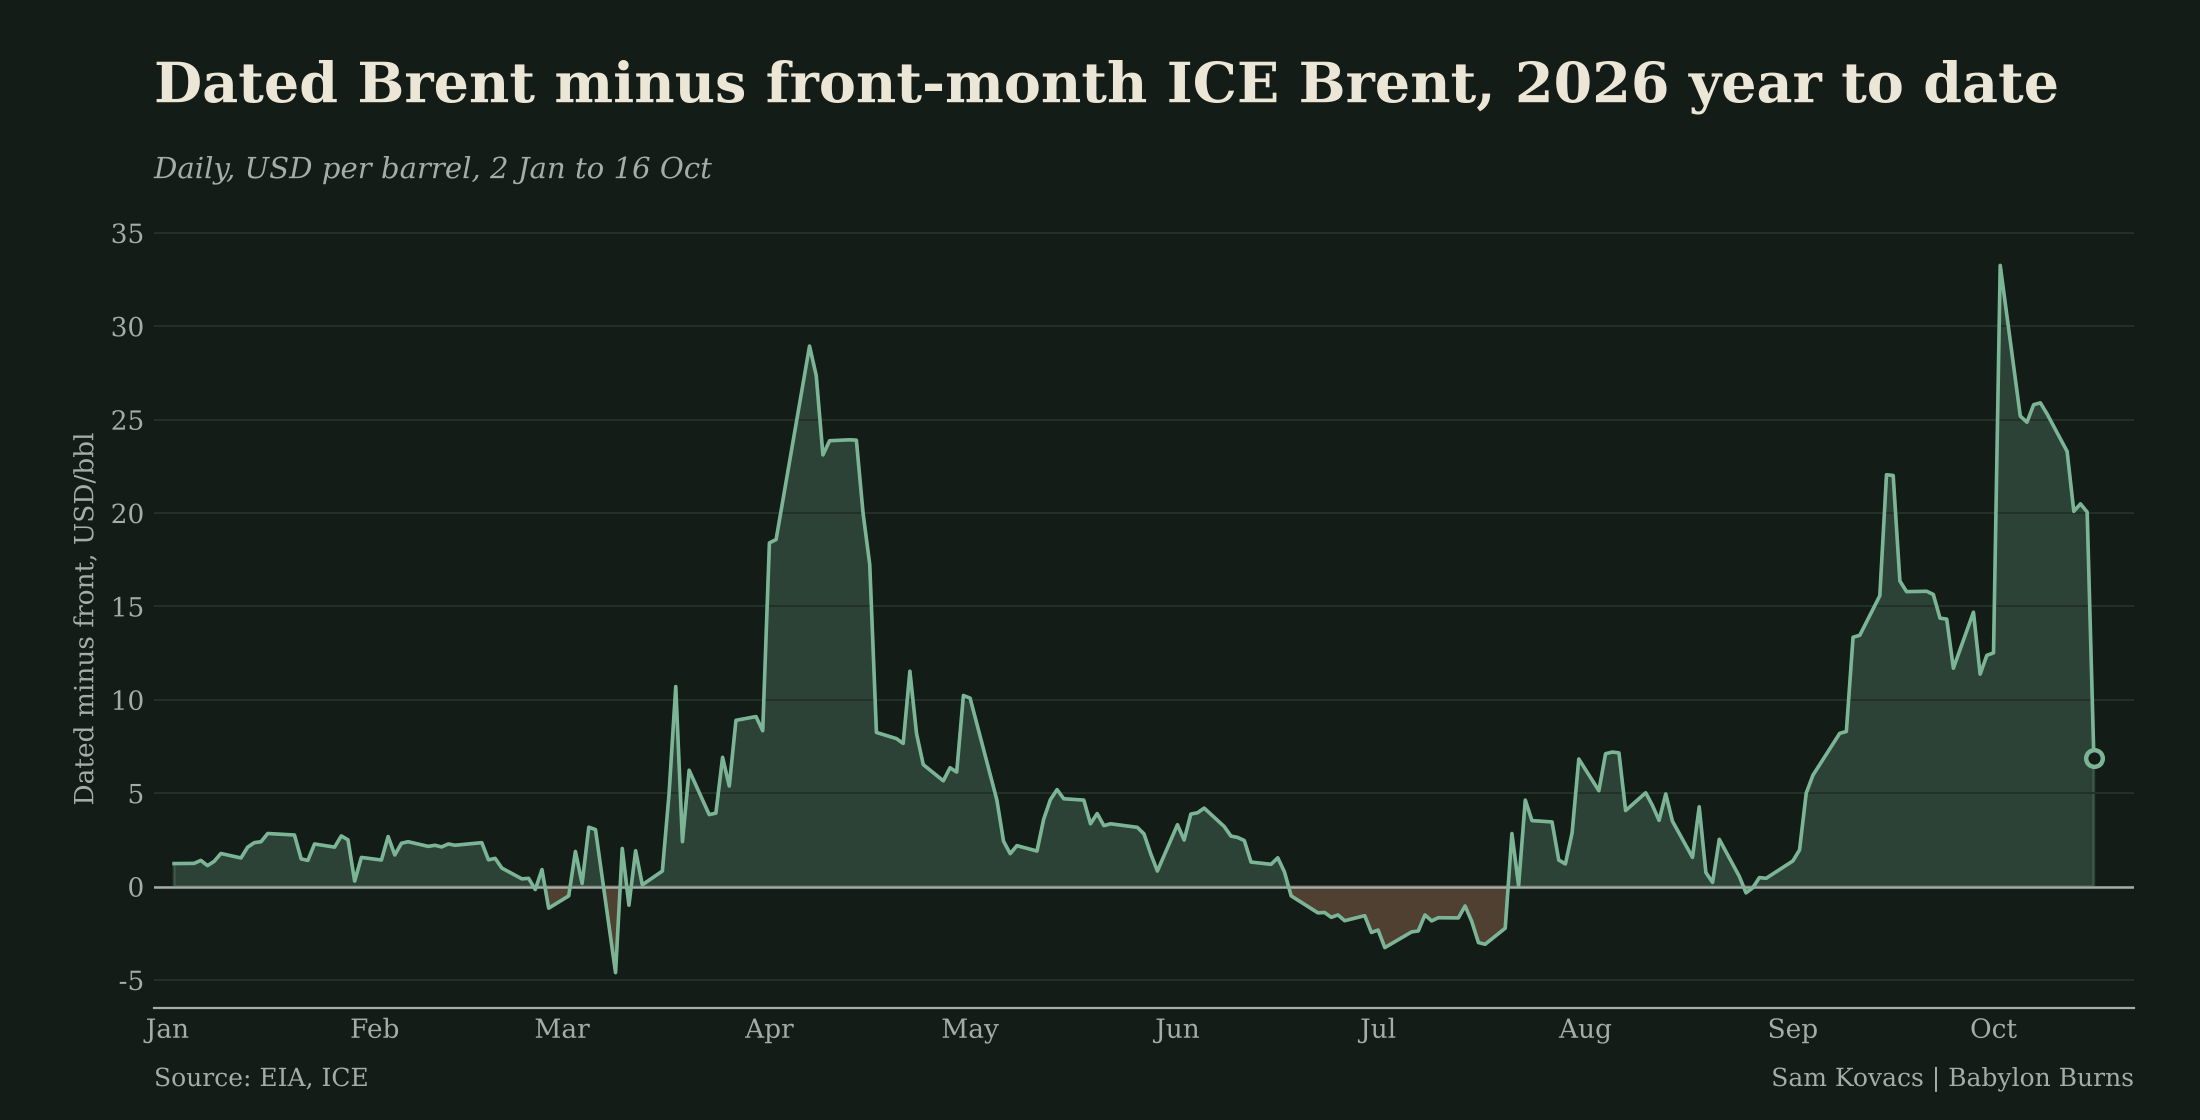
This was highly unusual, and X spaces popped up discussing whether this was insider trading, whether we were going to have war this weekend, and/or whatever spin people wanted to put on it. I instead decided to go back through every single trading day since July 2007, which is 4,737 sessions, to see if this convergence of front month up, Dated down, had happened before at any meaningful size. In the past 19 years, it has not.
The spread between Dated Brent and the front month went from a $20 gap to a $7 gap in one session.
In this article I’ll be:
Explaining the linkage between Dated and front-month Brent. Never be confused about them again.
Analyzing what happened in March and April, and why this looks different.
What I believe truly happened on Friday.
And all I am asking of you to read this article is your email address. I spend a lot of time researching these topics and writing these reports. I put out a lot of information for free.
Handing over your email address in exchange for honest analysis which will help you navigate the markets seems like a pretty good deal to me.