

This is a free report. If you like this, consider subscribing. I send out free analysis once in a while so you’ll get something while you decide if you want to pay.
Yes, I did say it was the BIG LONG, and I’m still saying exactly that.
(If you didn’t read that please check it out here)
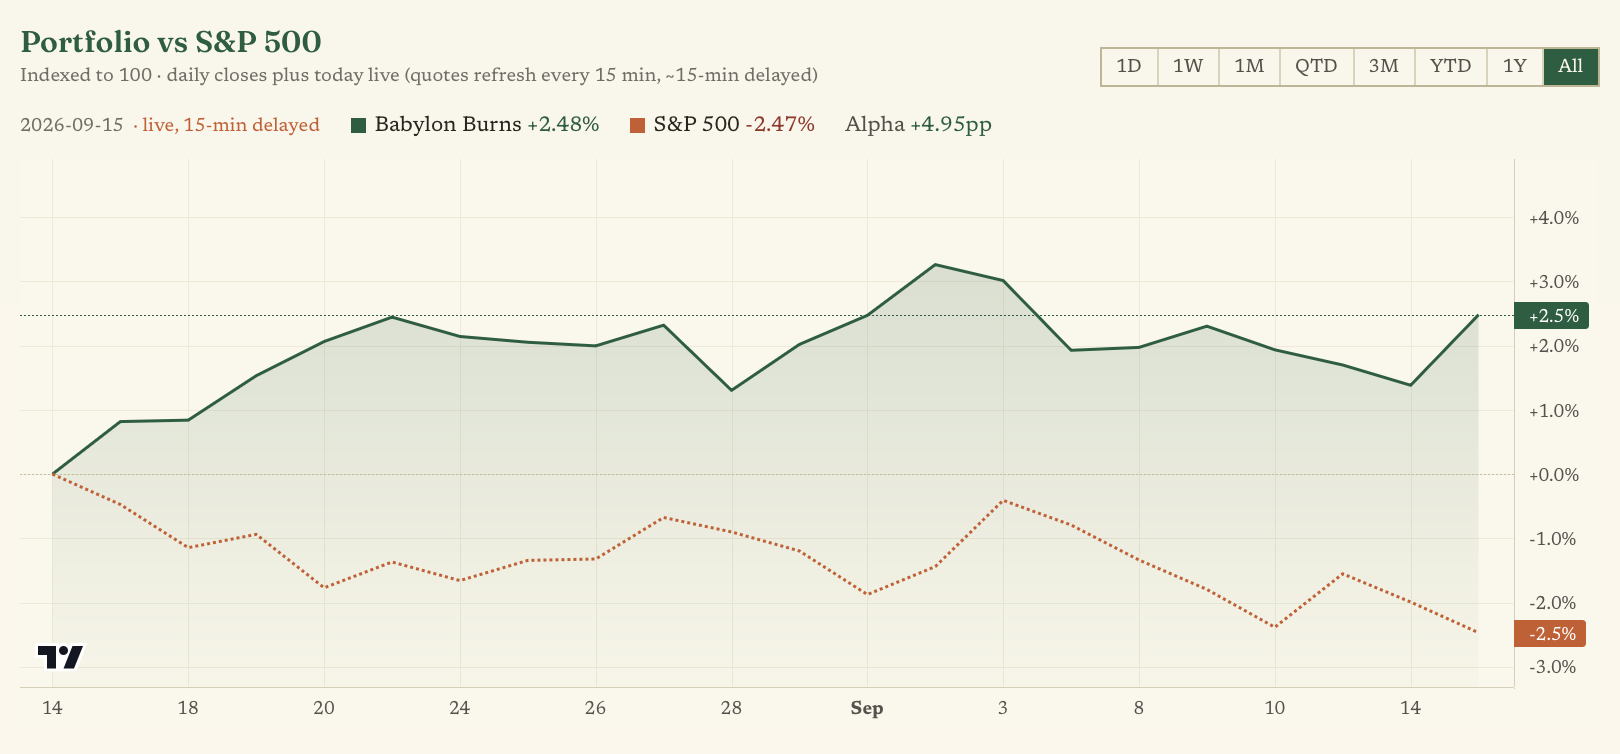
It has been a month since we started the Babylon Burns portfolio, and so far it is doing just ok.
We’re up 2.5%, while being 80% invested and 20% cash, while the S&P 500 is heading lower (down 2.5% since August 15th).
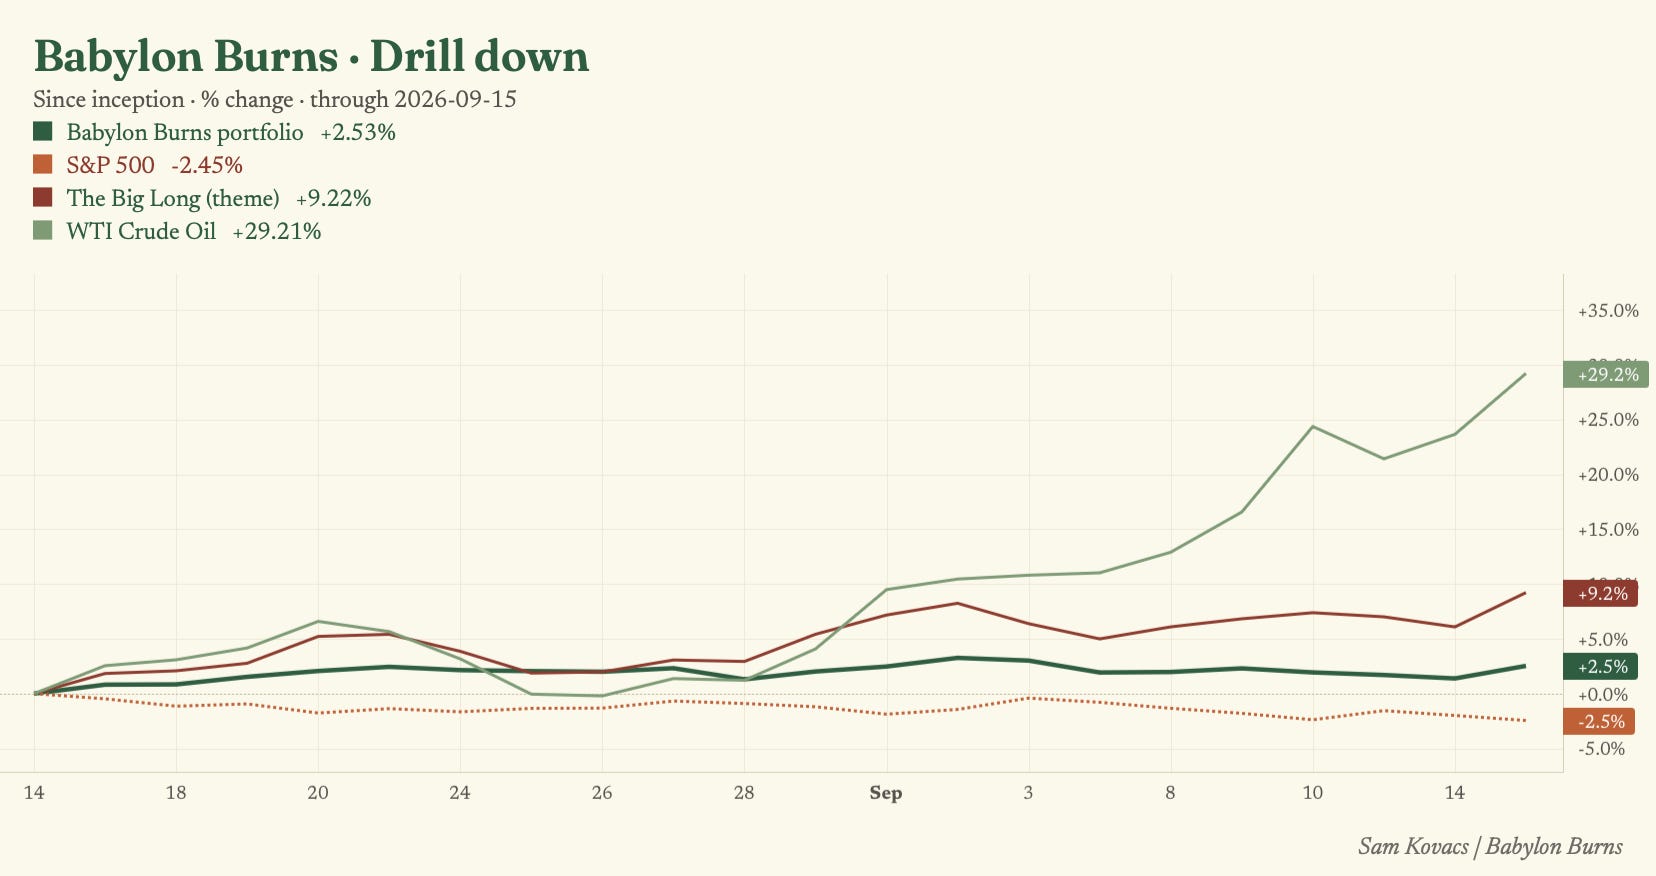
My stock picks which are linked to my “The Big Long” theme, have driven a lot of those gains as they are up 9% in a month.
Now that’s a fine and dandy 1 month return, but with WTI crude oil breaking to $106 as I write this, up 29% in a month and up 4.8% today alone, members are asking why the oil stocks are not following the front contract of WTI.
That’s mostly because the number you see on the screen when you look up WTI crude oil doesn’t matter as much as you think it does.
If we look at the curve at close yesterday. The barrel for delivery next month was $101.54 (granted its higher today). The barrel for delivery in March was $84. The barrel for delivery a year out, September 2027, was $74.54.
So the market is telling you that if you want oil right now, you pay a hundred bucks, but if you can wait a year, it is $75
That $27 backwardation gap is the biggest thing in the oil market right now.
Now think about what an oil company actually is.
It is a pile of barrels in the ground that come out over up to twenty years. When you value that pile, you use the strip, the whole curve of prices for every year going forward.
And the strip says $75 next year and the low seventies after that. So the market is valuing your E&P stock on $75 oil. The extra $27 on the barrel it sells this month is a nice bonus for a quarter or two.
In the eyes of the market, it does not change what the company is worth.
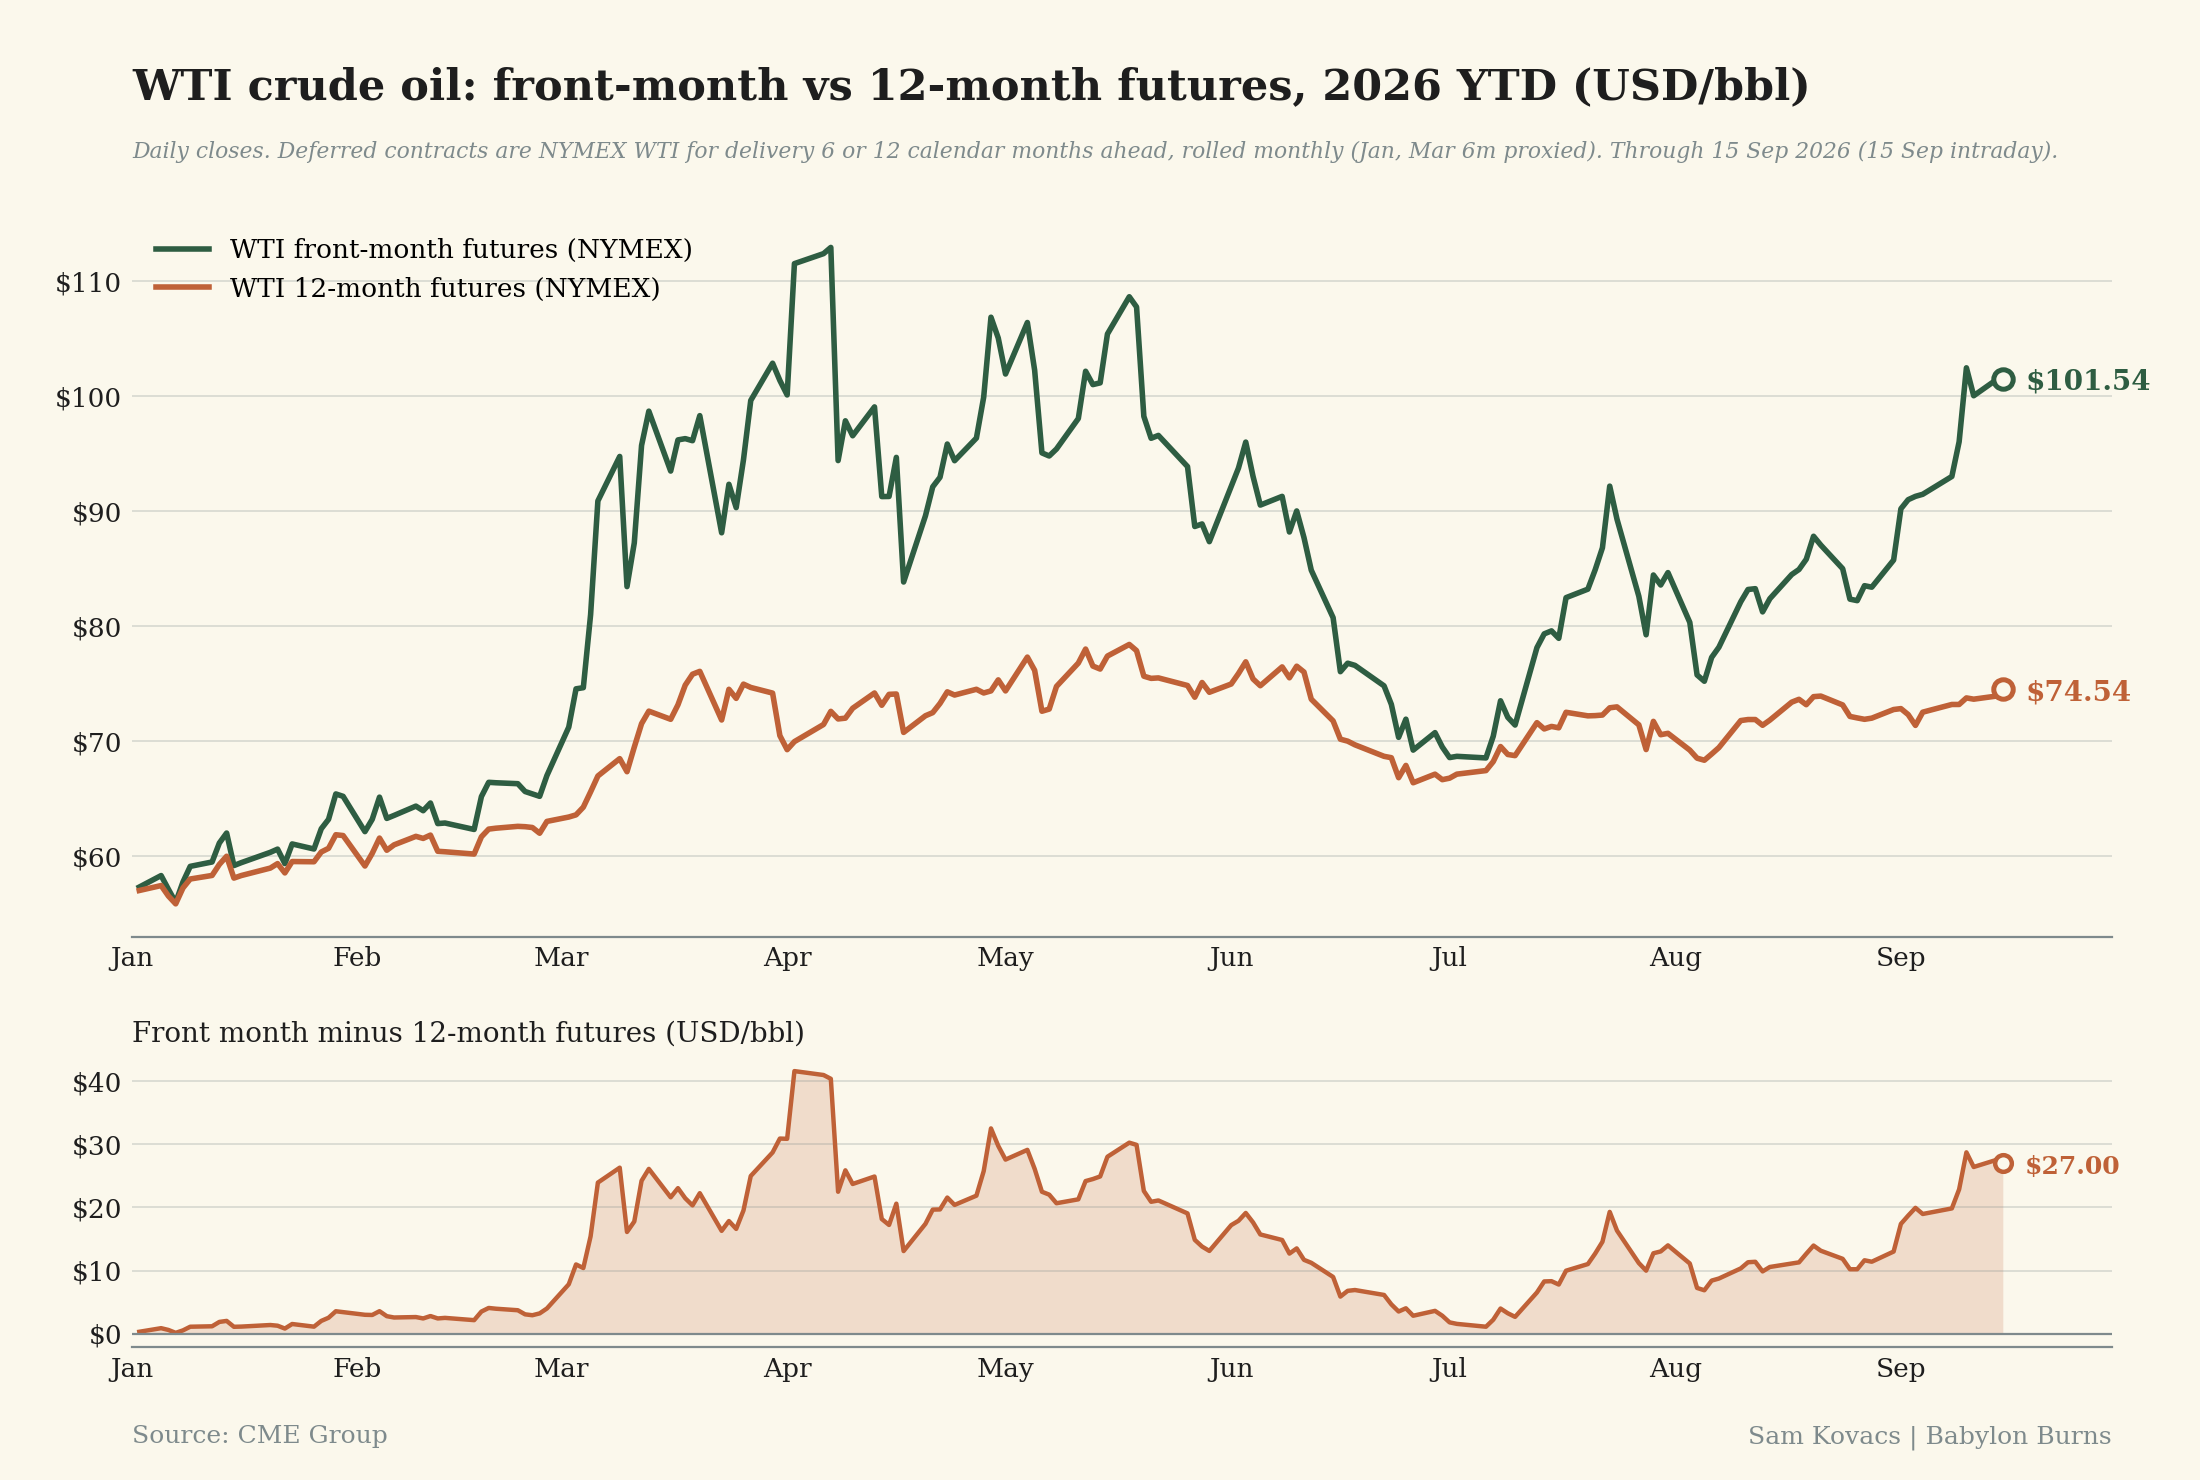
As you can see throughout the conflict, the spread between front month and 12 months widened dramatically: this is the market saying that this isn’t going to last a year.
The 6 month shows a similar spread.
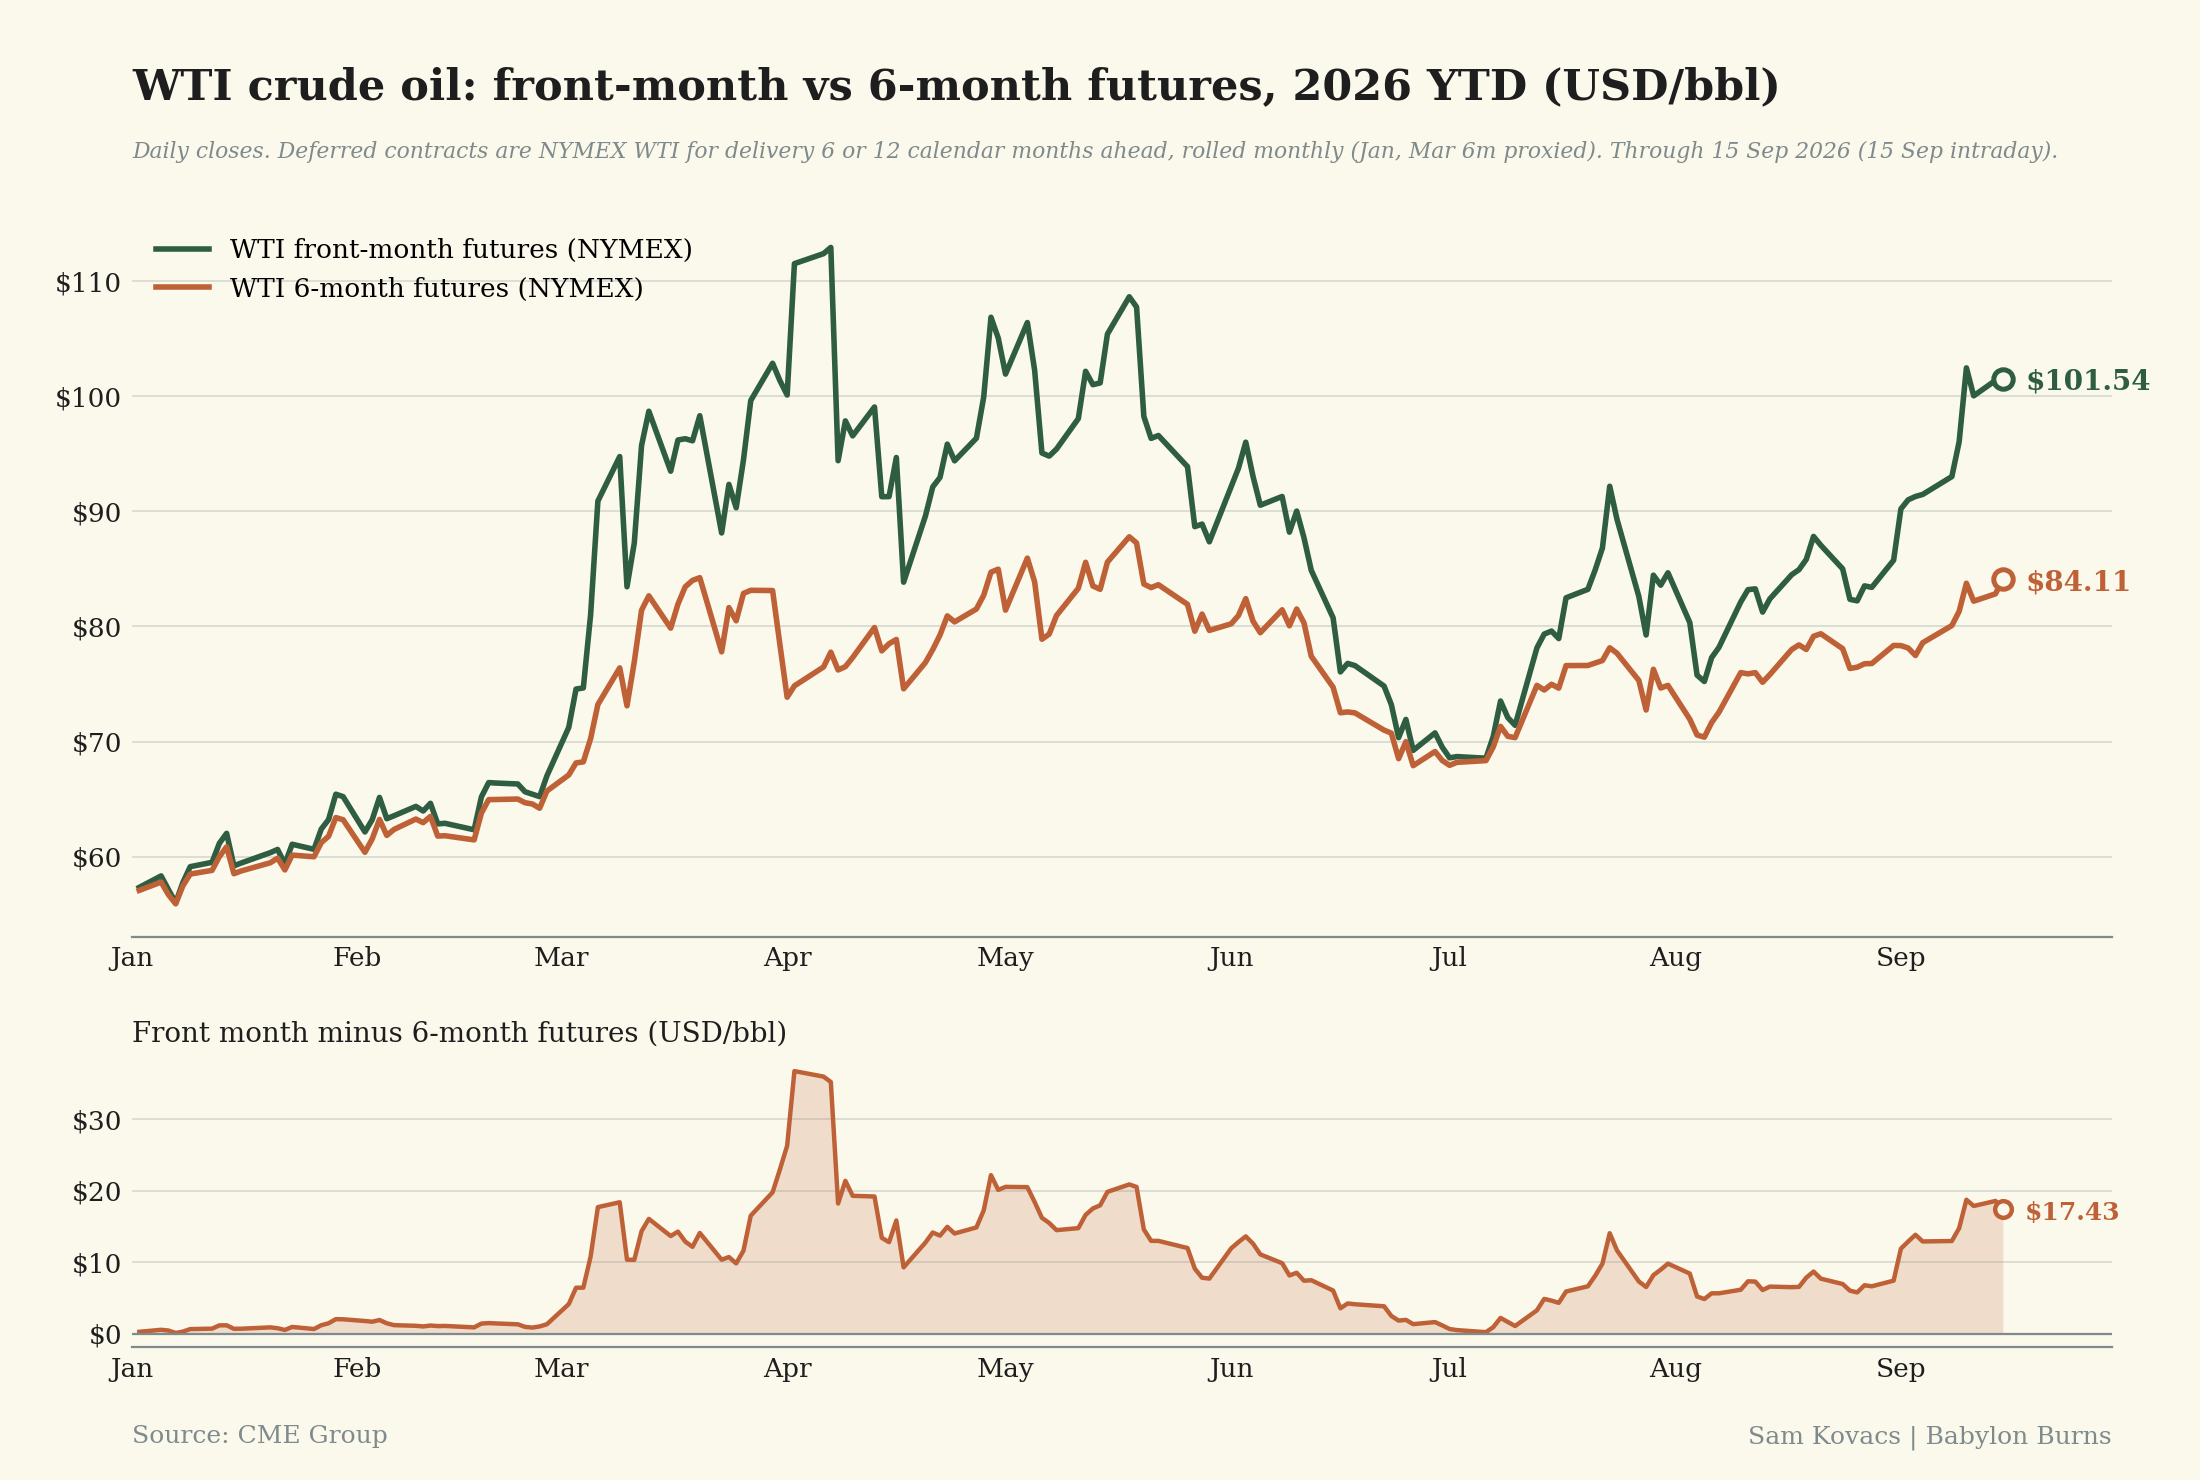
So what you’re seeing is the market saying that in 6 months oil should be $84 and in 12 months oil should be worth $75.
The cashflow over the next 12 months is the single biggest input into the valuation of an oil reserve (as it is the least discounted).
It is therefore natural that stocks move more in line with the 6-12 month segment of the curve, than with the front of it.
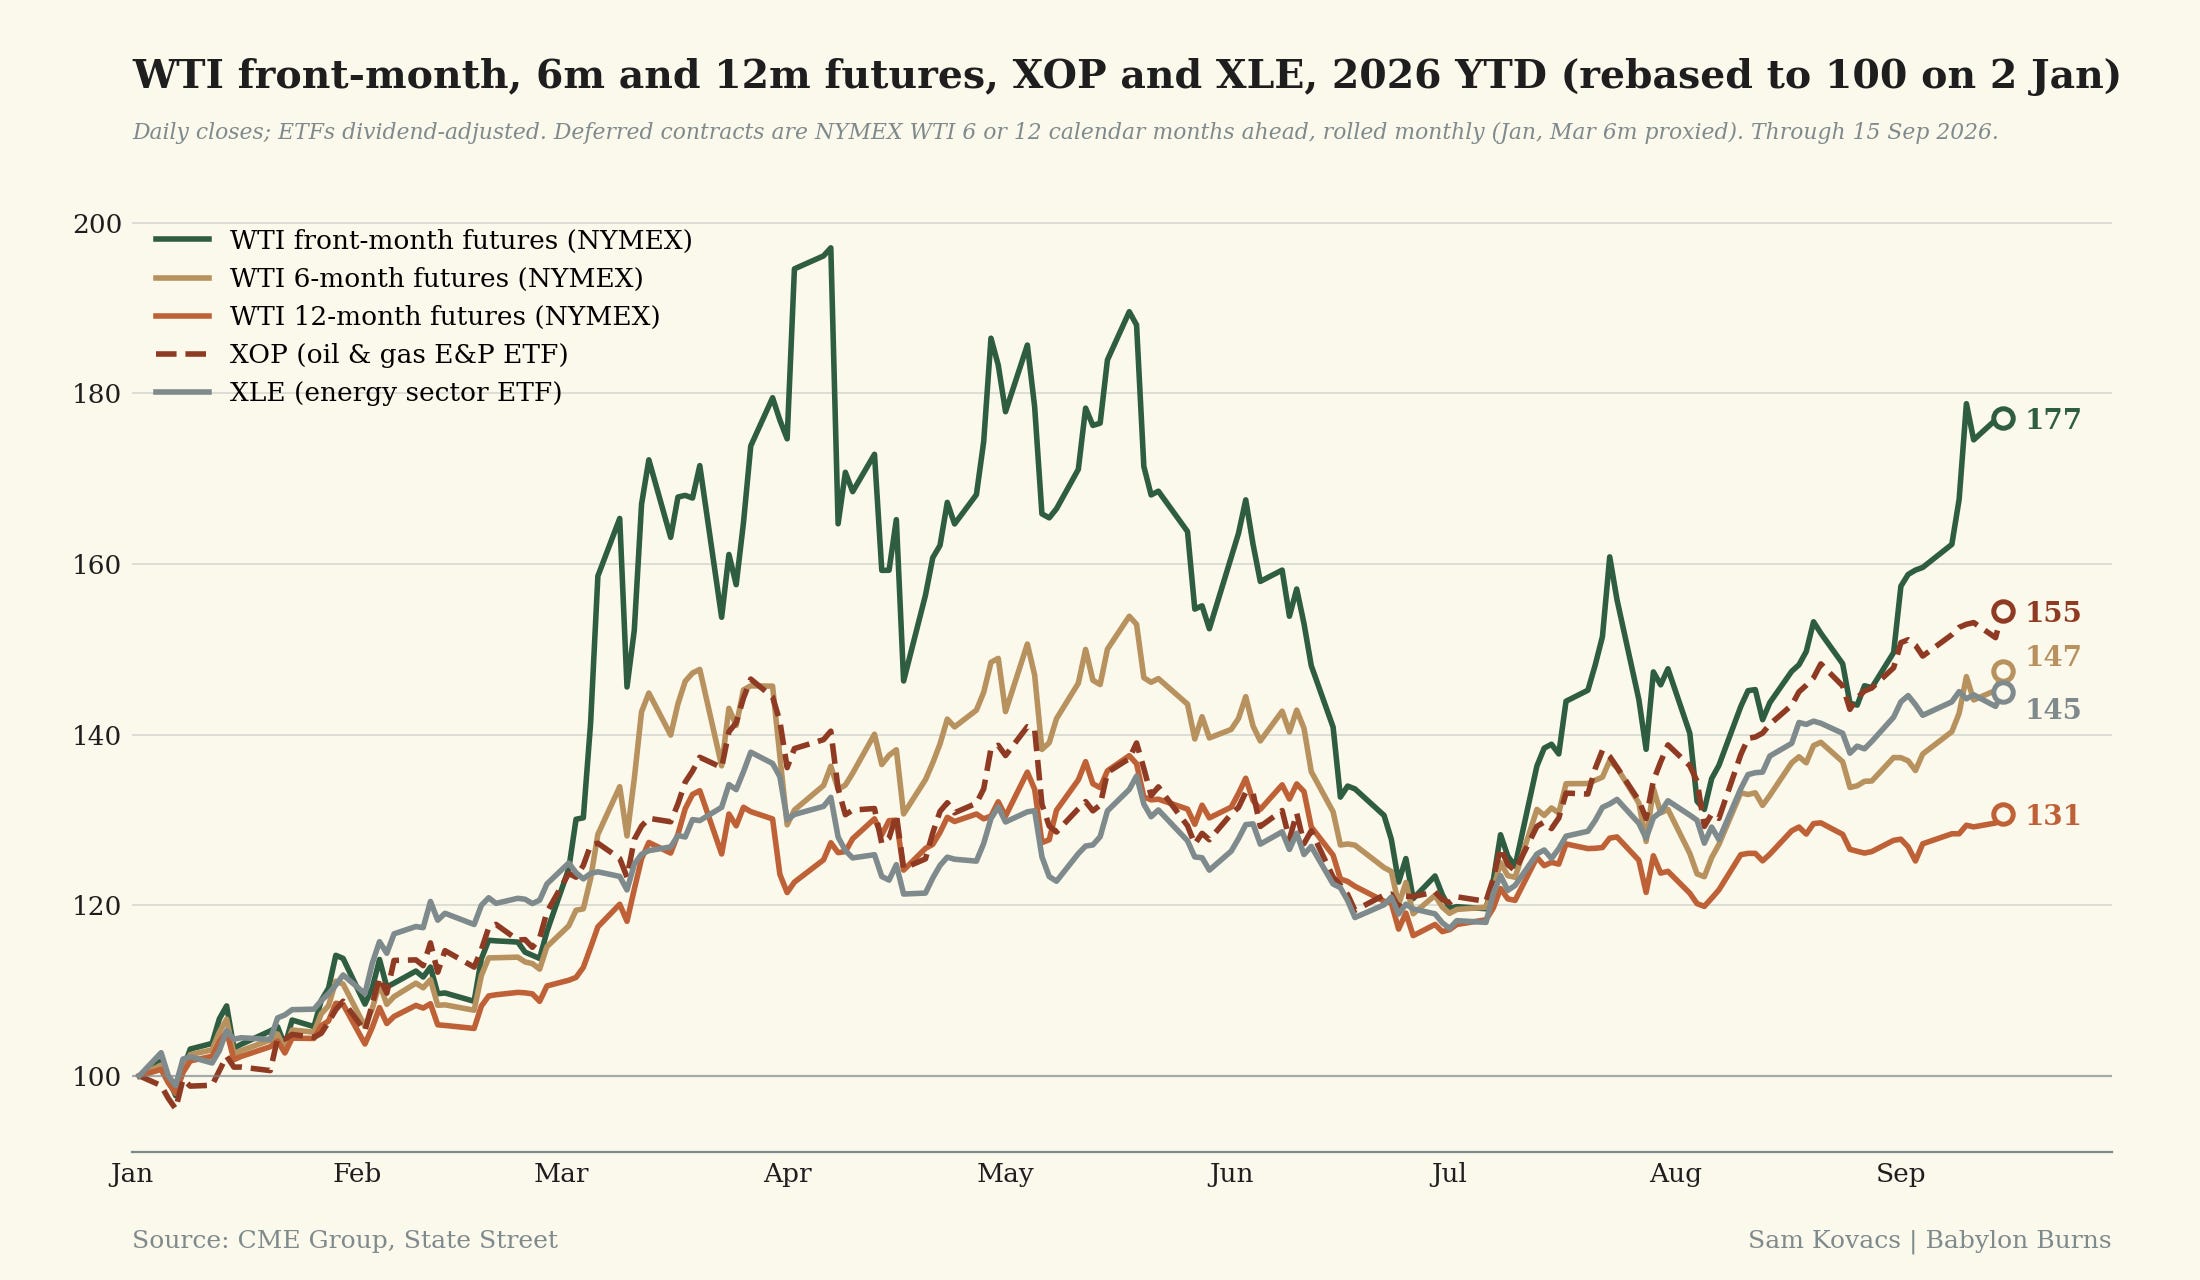
The behaviour since July has been different than it was in between Feb and June.
During the first spike, the price of oil stocks (as measured by XOP and XLE) were muted relative to the moves in the 6 and 12 month futures. The equity market was buying it even less than the futures market.
Now this has changed, and even the slower moving XLE has gained as much as the 6 month future has (assuming monthly rolling), this year.
For oil stocks to really rip, we need to see the curve flatten.
And I think they will.
It has now been revealed that the East-West Pipeline has sustained massive damage with 2 pumping stations taken out in attacks.
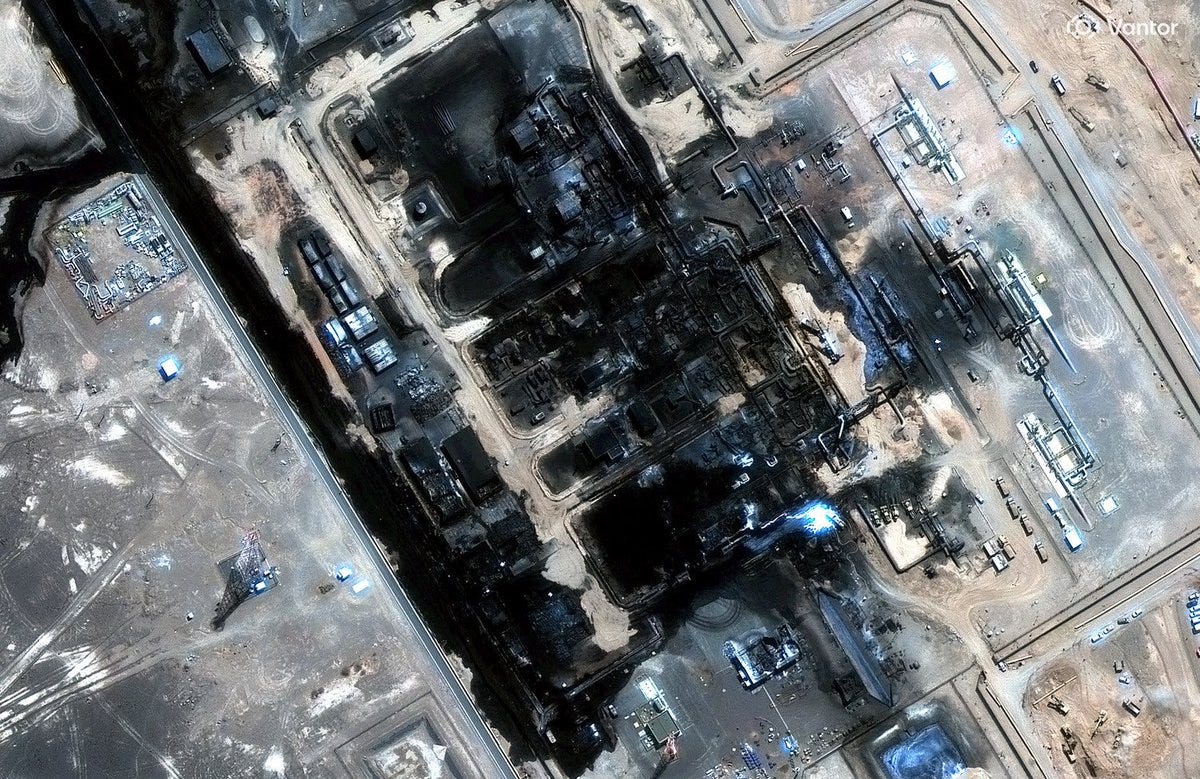
Saudis have been cancelling loadings for end of September, and word on the Street is they aren’t promising anything to customers before November.
Yes there is oil coming out of the Omani route, even if those VLCC tankers are constant targets of the Iranians who keep setting them on fire.
Maybe it’s 7mbpd. Maybe it is 10mbpd. Compared to 20 (22 if we take out the 2 from East-West now), that’s still a lot of oil that’s not coming out, and it is still a big problem
A 10-15mbpd gap isn’t solved by demand destruction of 2mbpd…
If you want more honest analysis hit that subscribe button to get my research into your inbox.
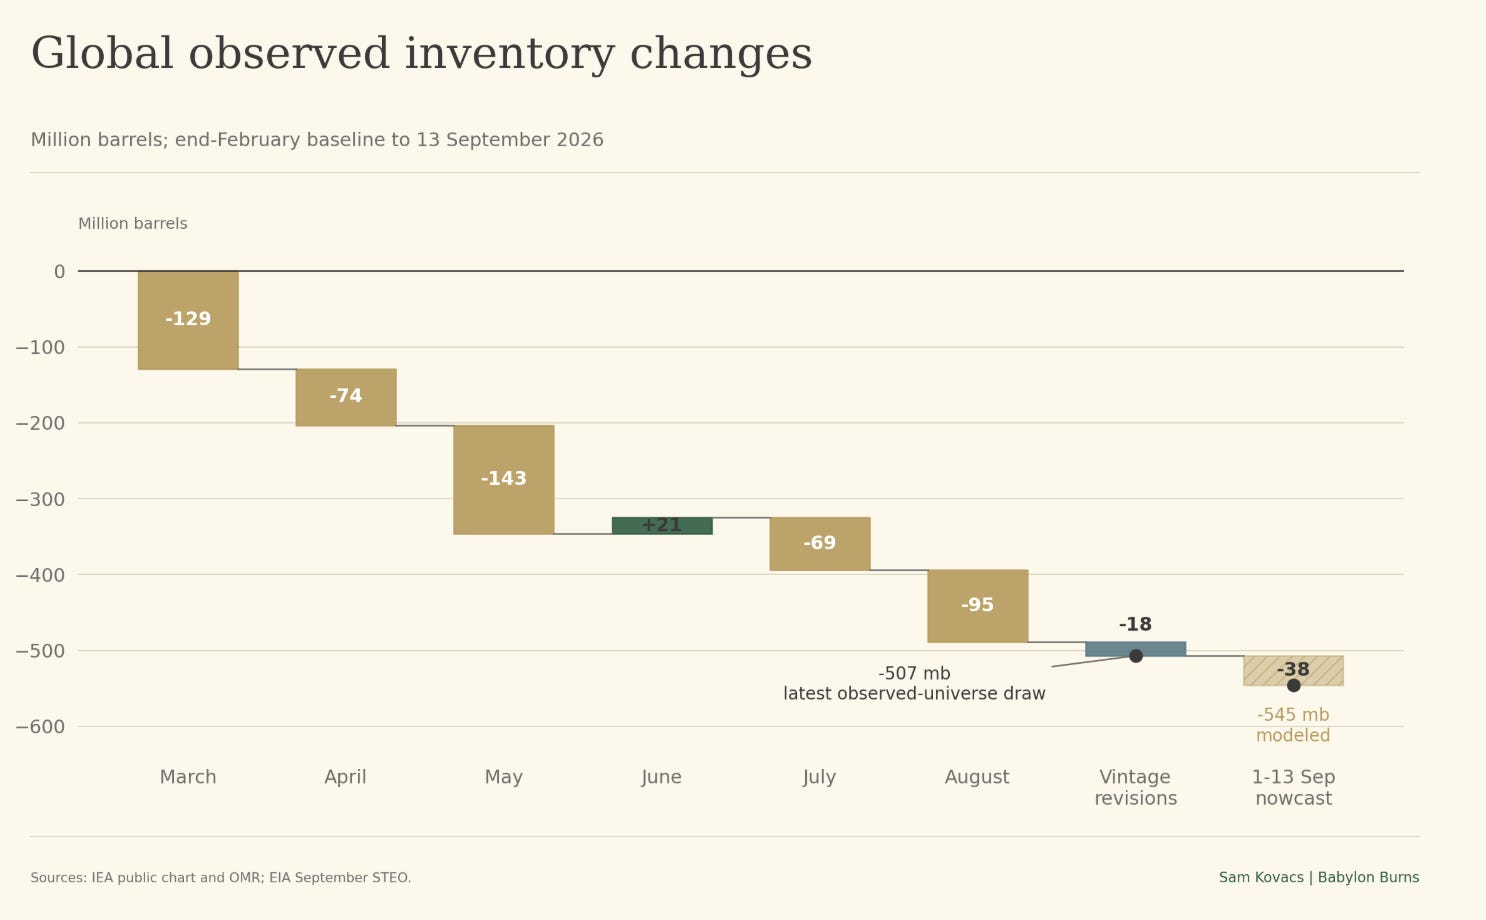
Global inventories have seen 500-550 million barrels drawn out of global inventories.
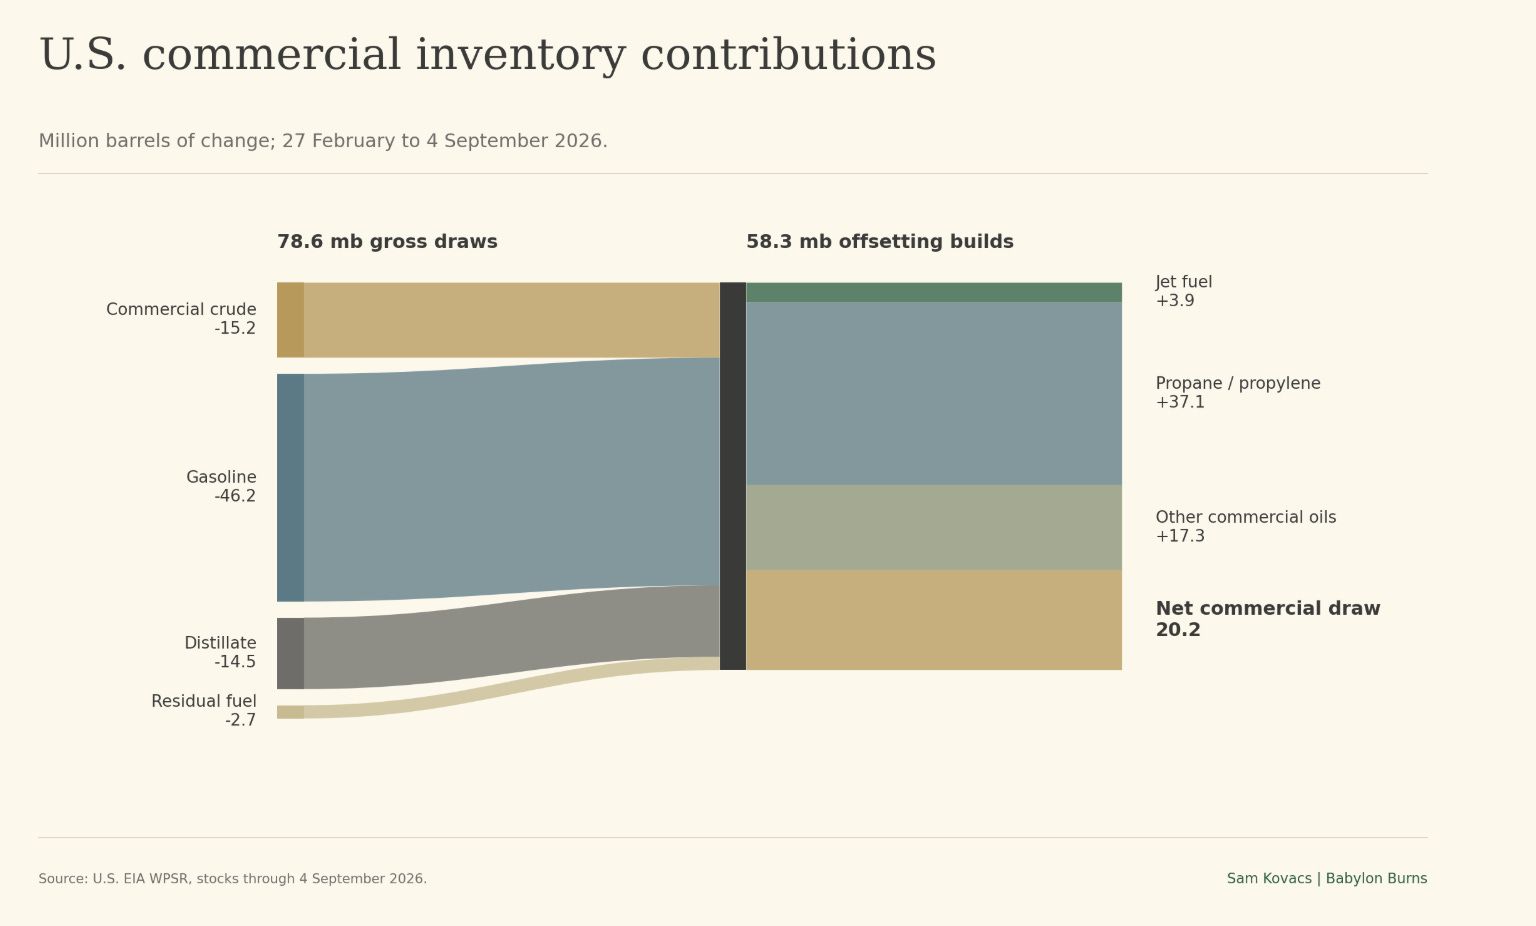
The numbers in the US are bad too. Commercial crude down, gasoline, distillates down. A propane build doesn’t make up for this.
The US is talking about filling up the SPR now, which would be incremental demand and removal of supply from the past few months.
Look, the market is slowly coming to grips with what I’ve been saying since March:
This crisis ain’t over ‘til it’s over. Global inventories are flirting with stress levels. There will be no second chance.
Front contract might continue to spike, but more importantly, the back end of the curve will start to lift as we realize that a resolution isn’t just around the corner.
That’s what would drive the true returns in energy stocks. In the meantime we have to accept the front end of the curve pulling everything up, but in an increasingly backwardated manner.
My thesis is the same as it has always been: This conflict is harder to resolve, we’re not going back to pre-war flows, there is no quick source of new oil, the one that exists hasn’t come back.
So stay humble, and stay the course. Some things take time.
As Babylon burns, we’ll light the cigars.
I have a variety of picks that stem from this conflict from producers, to gas stocks, to chems, to Canadians, to Atlantic basin picks.
Members receive live notifications when I trade so they never miss a pick.
If that sounds like something you want, join us.